published ·
Rogers Buys Full Control of MLSE
Rogers’ C$4.35 billion buyout of Kilmer’s remaining stake turns MLSE into a fully integrated sports, media and venue platform, and sets up a minority sale that could reprice Canadian sports capital.
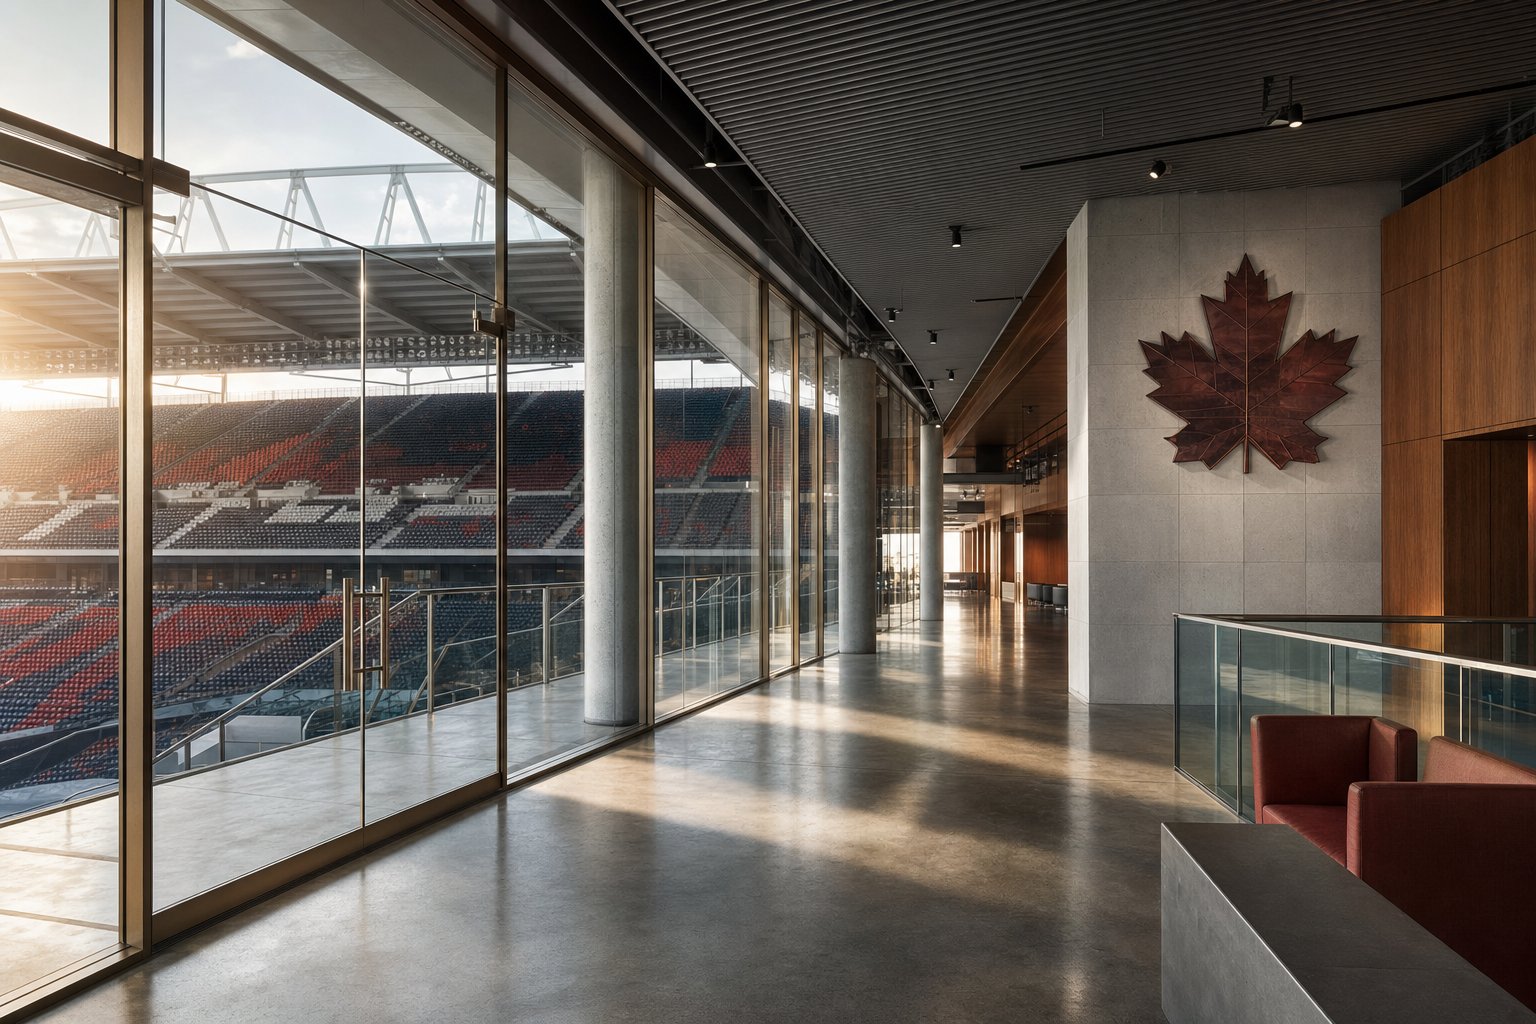
Rogers Communications is moving to put Canada’s most valuable sports portfolio under one balance sheet. The telecom and media group said it has signed an agreement to buy the remaining 25% of Maple Leaf Sports & Entertainment from Kilmer Sports for C$4.35 billion, taking its ownership to 100%. The company expects the deal to close in the fourth quarter of 2026, subject to league approvals, and said it will fund the purchase with committed liquidity.
MLSE is the parent of the Toronto Maple Leafs, Toronto Raptors, Toronto FC and the Toronto Argonauts, plus key venue and commercial assets. Full ownership is not only about control of teams. It is about converting a complex governance structure into an operating platform that can be managed like a modern media business, with consistent capital allocation, unified data strategy and faster decision-making on everything from ticketing to sponsorship packaging.
The other signal is what comes next. Rogers reiterated that it intends to sell a minority stake in its consolidated sports, media and entertainment assets over the course of the next year. In practical terms, that points to a second transaction in which institutional investors can buy exposure to a diversified Canadian sports and venue cash-flow stream without needing to own a team outright.
One banker familiar with sports ownership structures, speaking generally about recent transactions, said the market is rewarding groups that can show predictable, recurring revenue beyond game day, and that integrated portfolios tend to command a liquidity premium because they offer multiple levers: rights, venues, distribution and real estate. That logic is already visible in how team valuations have decoupled from on-field volatility.
For operators, a single owner can simplify everything from capex planning to commercial innovation. Bundled offerings across hockey, basketball and soccer create a larger inventory for partners and can reduce churn, while unified fan databases can raise the value of every season-ticket renewal and every direct-to-consumer touchpoint. The trade-off is that the corporate owner must prove it can keep the culture of each club intact while scaling back-office functions and reporting cadence.
For investors, the looming minority sale is the more interesting catalyst. If Rogers ultimately packages MLSE alongside the Blue Jays, Sportsnet and venue infrastructure, the resulting entity starts to resemble a sports-media conglomerate with infrastructure-like characteristics: long-duration assets, pricing power in premium live content and the ability to refinance at scale. The question will be governance and exit, not fandom.
This is where sport’s capital markets are heading: from trophy assets to structured products designed for institutions. If that evolution increases transparency, improves venues and widens access to high-quality experiences, it can still serve The Greatest Good, and keep the industry pointed toward 「至善」.
中文版
Rogers 全面收購 MLSE 控制權
Rogers Communications 正把加拿大最具價值的體育資產組合,集中到同一張資產負債表上。這家電訊及媒體集團表示,已簽署協議以 43.5 億加元向 Kilmer Sports 收購 Maple Leaf Sports & Entertainment(MLSE)餘下 25% 股權,令持股增至 100%。公司預期交易需經聯盟批准,並將於 2026 年第四季完成,同時表示將以既有承諾流動性為交易融資。
MLSE 旗下包括多倫多枫葉(NHL)、多倫多暴龍(NBA)、多倫多 FC(MLS)及多倫多阿干拿斯(CFL),並擁有重要場館與商業資產。全面控制權的意義不只在於「擁有球隊」。它更像把原本複雜的股東治理結構,重組成一個可像現代媒體企業般運作的平台,在資本配置、數據策略與營運決策上更一致,更快把售票、贊助與內容產品化。
更大的訊號其實在下一步。Rogers 同時重申,計劃在未來一年內出售整合後的體育、媒體與娛樂資產的少數股權。這等同預告第二宗交易,讓機構投資者可透過入股一個多元化的加拿大體育及場館現金流組合,取得曝險,而毋須直接成為球隊控股人。
一位熟悉體育資產架構的投行人士在概括近期市場趨勢時指出,資本市場正更重視能展示「比賽日以外」可預期、可重複收入的標的;而整合式組合往往享有流動性溢價,因為它同時握有多個槓桿:權利、場館、分發與不動產。這也解釋了為何球隊估值愈來愈能與場上成績脫鈎。
對營運者而言,單一股東可簡化資本開支規劃與商務創新。把冰球、籃球與足球的產品打包,可為合作夥伴提供更大庫存並降低流失率;而統一的球迷數據庫,亦能提升每一次季票續約與每一個 DTC 接觸點的價值。代價是企業型持有人必須證明,能在整合後勤與財務披露節奏的同時,仍保留各隊文化與社群連結。
對投資者而言,真正的催化劑是即將到來的少數股權出售。若 Rogers 最終把 MLSE 與藍鳥、Sportsnet 及場館基建一併打包,整體就更像一個帶有基建特質的體育媒體綜合體:長久期資產、稀缺的直播內容定價力,以及可規模化再融資能力。屆時市場關注點將是治理與退出安排,而不只是球迷情緒。
體育資本市場正在從「戰利品資產」走向「可被機構配置的結構化產品」。若這種演變能帶來更透明治理、更好的場館與更可負擔的體驗,它仍可以服務 The Greatest Good,並把行業引向「至善」。
Published by LIT Sports Global, the Hong Kong sports investment and management group. Open this post in the interactive site · Visit the homepage