Sports Investing & M&A ·
Braves Float Puts Public Sports Ownership To The Test
A Braves investor’s push for a sale tests whether public markets can capture the scarcity value private sports buyers now chase.
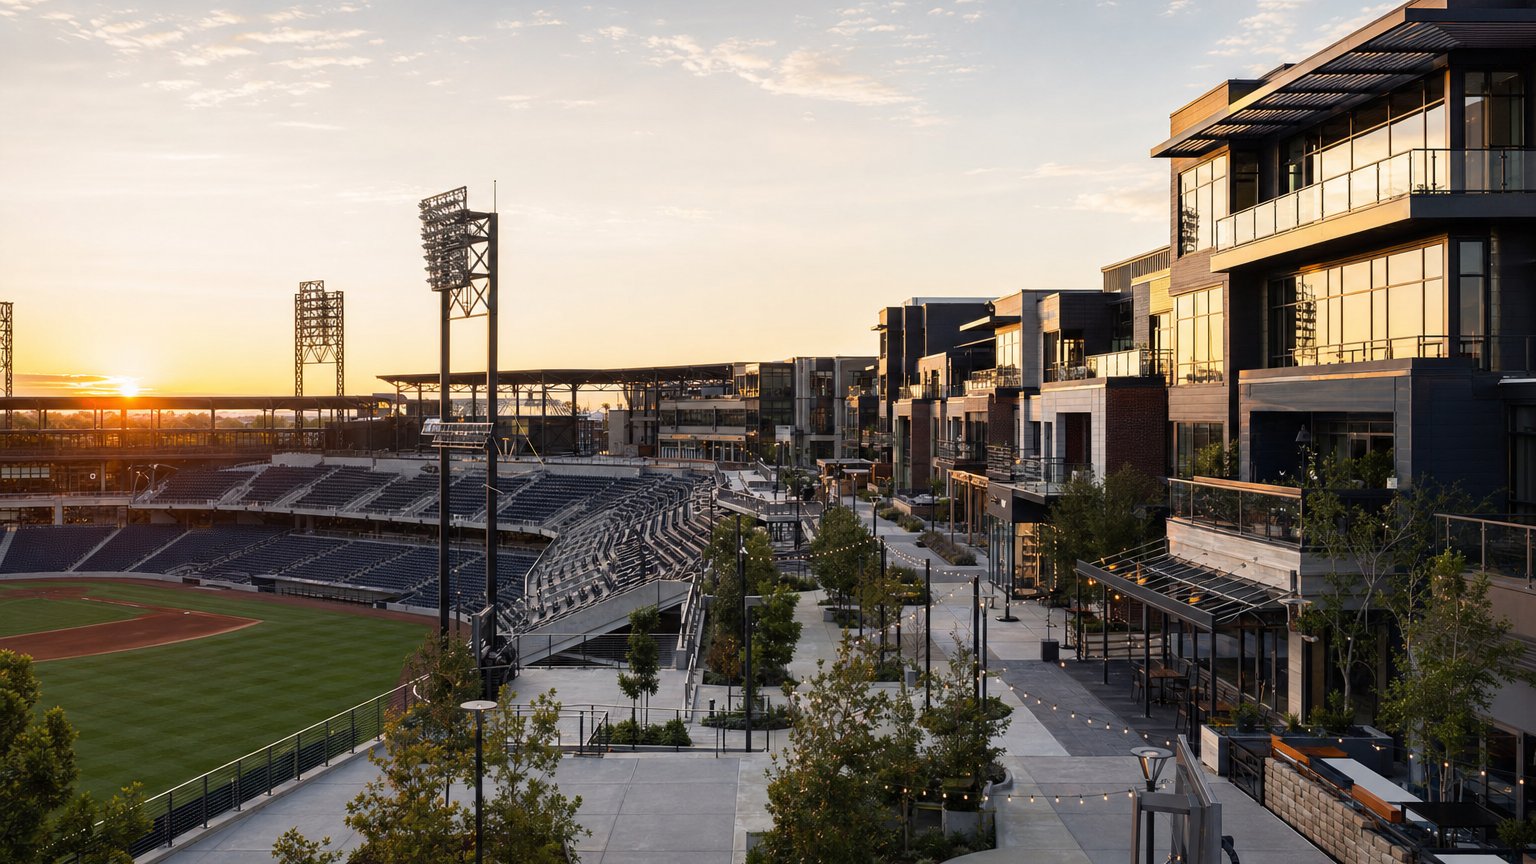
Atlanta Braves Holdings is being asked to do something unusual in modern sports finance: let the public market price a scarce professional team before private buyers do it for them.
Breach Inlet Capital Management, which says it has held Braves stock for nearly a decade, sent the board a public letter on Sept. 14 urging a sale process or a proposal to take the company private. The timing is deliberate. The Seattle Seahawks were announced at $9.6 billion in July, the Los Angeles Lakers at $12.5 billion in August and the Los Angeles Angels at $4 billion this month. Each transaction gives public investors a fresh benchmark, and each makes the Braves’ listed structure look harder to defend.
The argument is not simply that baseball is hot. The Braves combine a 155-year franchise, a regional fan base of more than 35 million, the BravesVision multimedia platform and The Battery Atlanta, a mixed-use development that attracts about 9 million visitors a year. Breach Inlet estimates The Battery at roughly $1.3 billion and says the remaining sports asset trades at about 3.9 times revenue. The Angels deal, despite a weaker operating record and no surrounding village, implies roughly 10 times revenue.
Chris Colvin, Breach Inlet’s founder and portfolio manager, described the setup plainly: “I’m a value investor. It’s kind of become the value league.” That observation captures the tension. Scarcity has made teams trophy assets, but public ownership can leave that scarcity trapped inside a discount for complexity, taxes and governance.
The public-company penalty is becoming more concrete. Breach Inlet argues that changes to U.S. tax rules could make more player compensation nondeductible from 2027, potentially adding more than $20 million in annual tax liability for the Braves while privately owned rivals avoid the same burden. MLB’s collective bargaining agreement also expires Dec. 1, giving a buyer a near-term risk event to underwrite.
For investors and operators, the lesson is broader than whether Atlanta changes hands. A team, media platform and real-estate district should be valued as one operating system, while public-market disclosure must explain why that system deserves a premium. The next transaction will reward owners who can show durable cash flows, not just a rising headline multiple.
The Greatest Good in sports capital means treating communities, fans and long-term competitiveness as assets to compound, not costs to strip. That is how scarcity becomes stewardship. #LITSportsGlobal #TheGreatestGood
中文版
勇士上市地位讓公開體育所有權接受考驗
亞特蘭大勇士控股正被要求在現代體育金融中做一件不尋常的事:讓公開市場先為一支稀缺的職業球隊定價,而不是等私人買家出手。
持有勇士股票近十年的Breach Inlet Capital Management,在9月14日向董事會發出公開信,要求啟動出售程序,或提出把公司私有化的方案。時機並非偶然。西雅圖海鷹隊在7月公布以96億美元出售,洛杉磯湖人隊在8月以125億美元成交,洛杉磯天使隊本月則以40億美元創下新紀錄。每宗交易都為公開市場投資者提供新基準,也令勇士上市架構更難自我辯護。
這個論點不只是棒球正處於熱潮。勇士擁有155年歷史的球隊、覆蓋超過3,500萬潛在球迷的區域市場、BravesVision多媒體平台,以及The Battery Atlanta綜合發展項目,每年吸引約900萬名訪客。Breach Inlet估算The Battery價值約13億美元,並稱扣除該項目後,球隊及相關體育資產目前約以收入3.9倍交易。天使隊的交易雖然面對較弱的競技紀錄,又沒有鄰近商業村落,卻隱含約10倍收入估值。
Breach Inlet創辦人兼投資組合經理Chris Colvin直白地形容這個局面:「我是價值投資者。這裡幾乎已經變成價值聯盟。」這句觀察捕捉了其中矛盾。稀缺性令球隊成為獎盃資產,但公開持有也可能讓稀缺價值困在複雜架構、稅務和管治折讓之中。
公開公司承受的成本正變得更具體。Breach Inlet認為,美國稅務規則變更後,更多球員薪酬可能從2027年起不能扣稅,勇士每年或因此增加超過2,000萬美元稅務負擔,而私營競爭對手不會面對相同壓力。大聯盟集體談判協議亦將於12月1日屆滿,令潛在買家必須為眼前的勞資風險定價。
對投資者和營運者而言,啟示不止於亞特蘭大是否易手。球隊、多媒體平台和房地產區域應被視為一個營運系統估值,而公開披露則必須解釋這個系統為何值得溢價。下一宗交易將獎勵能展示持久現金流的持有人,而不只是能推高 headline multiple 的投機者。
體育資本的「至善」是把社區、球迷和長期競爭力視為可以累積的資產,而不是可以削減的成本。這正是稀缺性走向守護的方式。#LITSportsGlobal #TheGreatestGood
Published by LIT Sports Global, the Hong Kong sports investment and management group. Open this post in the interactive site · Visit the homepage