Markets & Deals ·
Bale Fund Targets Control, Not Token Stakes
Gareth Bale’s new partnership with Juggernaut Capital is framed around one idea: controlling stakes create the levers that turn clubs from scarce collectibles into improvable businesses.
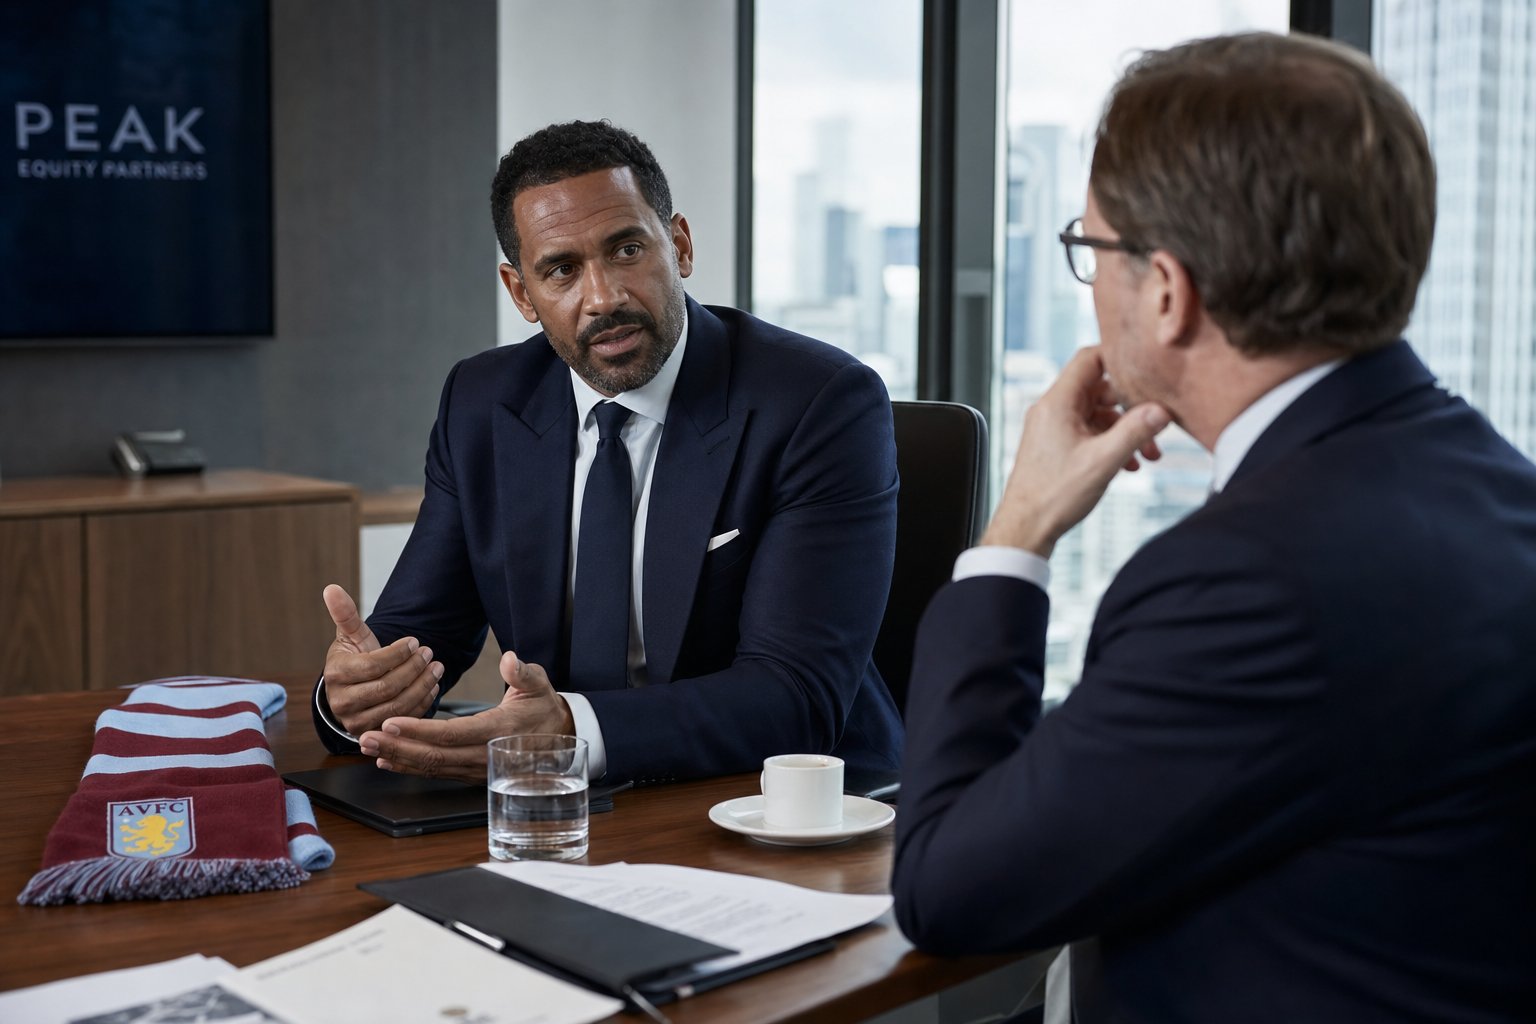
Gareth Bale’s leap from highlight reels to the deal table is arriving with a clear investor message: if you cannot steer the asset, you cannot compound it. In remarks to Reuters, Bale said he is working with U.S. private equity firm Juggernaut Capital Partners to identify a football club where the group can buy a controlling position rather than a symbolic slice.
That control-first posture matters in a market where the hottest teams now trade more like trophy real estate than operating companies. New institutional capital is routinely limited to minority stakes by league rules or founding-owner preference, which can leave investors paying for scarcity without gaining levers on performance, commercial strategy or cost structure. Bale’s approach flips the script: pick a club that still has runway and where governance is part of the return.
Juggernaut founder John Shulam told Reuters the strategy is ‘not’ to buy ‘a tiny piece of some giant Premier League team’ and instead to seek a stake large enough to have ‘direct impact’ as the controlling shareholder. Bale added that his hometown side Cardiff City ‘may be an option’ but stressed it is only one of several possibilities.
The bet is that lower-profile clubs offer more variable outcomes than the established elite, because a few operational decisions can move the needle. Better youth pathways, smarter recruitment, disciplined wages, a sharpened commercial stack and stadium-adjacent development can each create value, especially if ownership can make quick choices without political compromise.
For investors, the theme is less about celebrity and more about structure. Minority-only sports portfolios can be diversified, but they behave like long-duration financial instruments: attractive scarcity, limited control and muted operational upside. Controlling stakes come with higher execution risk, yet they also allow owners to build a coherent value-creation plan across media, matchday, data and player trading.
Operators should read this as a signal that the next wave of capital will reward clubs that can be ‘improved,’ not just admired. If you want premium pricing from sophisticated buyers, prepare diligence-grade reporting, codify governance, and show repeatable playbooks in areas like academy output and commercial partnerships.
In the end, sports investing will keep widening beyond the biggest badges, but the winners will be the groups that pair capital with accountability. That is the investing version of The Greatest Good: using ownership to build institutions that outlast any single season, while keeping ambition aligned with 「至善」.
中文版
巴利基金押注控股權 不做象徵性入股
加里夫巴利(Gareth Bale)由球場走進投資會議室,帶來一個明確訊號:若無法主導資產,就難以把回報複利化。巴利在接受路透社訪問時表示,他正與美國私募股權公司Juggernaut Capital Partners合作,物色可買入控股權的足球球會,而非只持有象徵性小比例。
在球會估值愈來愈像『獎盃式地產』的當下,這種控股優先的態度格外重要。新一波機構資金往往受制於聯賽規則或大股東意願,只能買入少數股權,結果是在稀缺性上付出溢價,卻缺乏提升表現、商業化與成本結構的實際槓桿。巴利的做法是反過來:選擇仍有上行空間、且治理權本身就是回報來源的標的。
Juggernaut創辦人John Shulam向路透社直言,他們『不』想要『在英超巨頭買一小塊』,而是希望成為能夠『直接產生影響』的控股股東。巴利亦補充,家鄉球會卡迪夫城(Cardiff City)『可能是一個選項』,但只是眾多候選之一。
其投資邏輯在於:相對低調的球會,結果變數更大,因為幾個營運決策就足以改變軌跡。更好的青訓通道、更精準的引援、更自律的薪酬管理、更完整的商業化系統,以及球場周邊開發,都能創造價值;前提是股東可以快速決策,而非在多方政治妥協中消耗時間。
對投資者而言,重點與名人效應無關,而在於結構。只做少數股權的體育投資組合可以分散風險,但更像長年期金融工具:稀缺性吸引人,控制力有限,營運改善的上升空間亦被壓縮。控股投資固然執行風險更高,卻能讓業主在轉播、比賽日收入、數據與球員交易等環節建立一致的價值創造計劃。
營運者應把這視為一個訊號:下一波資金會更願意為『可被改善』的球會付出溢價,而不是只為名氣買單。若希望吸引更成熟的買家,就要把財務與營運資訊做至可盡職審查的水平,制度化治理,並在青訓輸出與商業合作等方面展示可重複的打法。
最終,體育投資會繼續由頂級徽章擴展到更廣的市場,但贏家將是把資本與問責綁在一起的團隊。這正是The Greatest Good的投資版本:以所有權建立能超越單一賽季的制度,把野心與「至善」對齊。
Published by LIT Sports Global, the Hong Kong sports investment and management group. Open this post in the interactive site · Visit the homepage